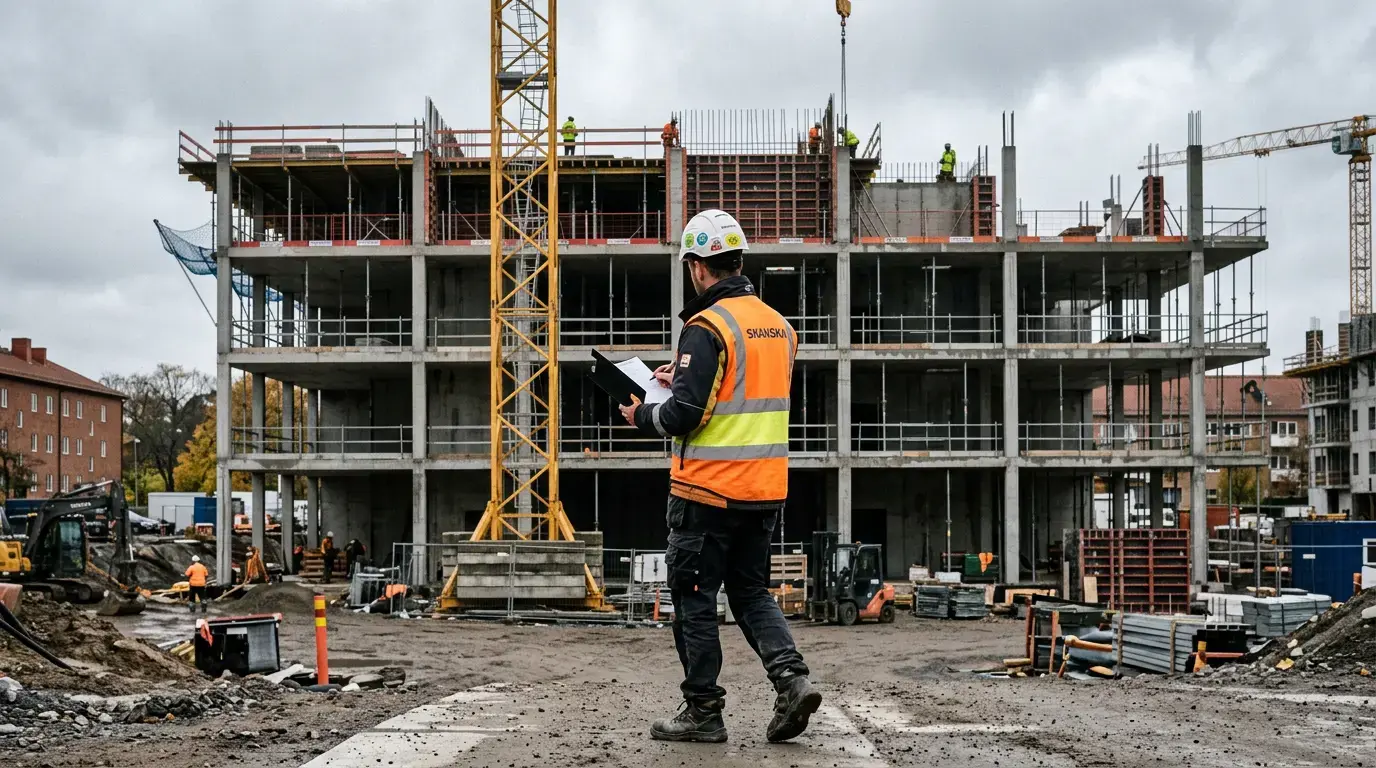
A document that most construction supervisors don't have until it's too late
Imagine this scenario: An experienced specialist is overseeing the renovation of an apartment building; everything seems to be in order, and the work is progressing smoothly. Six months after the project is handed over, the client files a claim—the facade cladding has come loose, cracks have appeared, and an expert assessment concludes that part of the blame lies with the technical supervisor, who failed to notice the defect in time. The amount claimed is several tens of thousands of euros.
Then an unpleasant reality comes to light. The person didn’t even know that his civil liability was supposed to be insured. And that without a valid policy, the entire amount falls on his shoulders.
This is precisely where the problem begins—one that is rarely discussed. Many people oversee construction projects for years without ever hearing about insurance for construction technical supervisors. Until the day they actually need it.
In shortCivil liability insurance for construction supervisors is mandatory in Lithuania—this is stipulated in the Construction Law. Without a valid policy, the supervisor risks having to personally compensate for damages, which can amount to tens of thousands of euros. Make sure you have valid civil liability insurance before starting any project, not after.
Why Does This Insurance Exist in the First Place?
The technical supervisor is responsible for ensuring that construction work is carried out in accordance with the project, standards, and quality requirements. This is a significant responsibility. If supervision is negligent, the client—and sometimes third parties—suffer the consequences.
The legislature has determined that the liability of professionals in this field cannot remain merely “on paper.” If a supervisor makes a mistake, the client must have a realistic way to recover their losses. Insurance acts as a financial safety net here—the insurer covers the damages first, rather than the specialist’s wallet being depleted.
And that is the crux of the matter. Insurance protects not only the client but also the supervisor themselves from a financial blow that could exceed several months’ or even years’ worth of earnings.
Who Is Required to Have This Insurance and When
This is where most of the confusion lies. Not everyone realizes that this is a legal obligation, not a voluntary choice.
The Construction Law stipulates that the civil liability of a building’s technical supervisor—whether an individual or a legal entity—must be insured. This means that, without a policy, it is technically impossible to legally perform technical supervision of special and non-special structures under the established conditions.
Warning: If the client or the authority issuing the building permit requests proof of valid civil liability insurance and you do not have it, you may lose the contract or be removed from the project. You may receive a claim even several years after the work is completed.
Insurance is required for:
- individuals working as technical supervisors of a building on a self-employed basis;
- companies providing technical supervision services;
- specialists hired by the client to supervise specific projects.
And how long should the policy be valid? For the entire duration of technical supervision, not just during construction. Liability for hidden defects may arise later, so it’s important to know exactly what period your coverage covers.
What happens if there is no policy?
Let’s say a maintenance technician is working without insurance and something happens that no one anticipates—a structural defect that went unnoticed during maintenance.
Without insurance, the chain of events looks something like this:
- The client files a claim or takes the matter to court.
- An expert assessment is conducted to determine the extent of the inspector’s fault.
- If liability is proven, the supervisor compensates for the damages out of their own pocket.
- If there is a dispute over the amount, court and attorney’s fees are added.
The cost of insurance usually amounts to only a small fraction of the sum that would have to be paid in a single lump sum if liability were actually triggered.
With a valid policy, the scenario is different. The claim is forwarded to the insurer, who assesses the incident and covers reasonable damages up to the policy limit. The policyholder pays only the deductible—their share as specified in the contract, the amount of which depends on the specific terms of the policy.
A specific example of when liability applies
A specialist is supervising the construction of a single-story commercial building. During supervision, he fails to adequately inspect the waterproofing work, and the contractor makes a mistake. After the winter, the building begins to flood, damaging the floors and equipment.
An expert assessment determines that part of the liability lies with the contractor and part with the technical supervisor, as the latter should have noticed and stopped the improper work. The total damage to the property amounts to 30,000 EUR, of which the supervisor’s share is 18,000 EUR.
|
With Insurance |
Without insurance |
| Supervisor’s share of liability |
18,000 € |
€18,000 |
| The insurer covers |
€17,000 |
€0 |
| The custodian pays out of pocket |
€1,000 (deductible) |
€18,000 |
The difference between the two scenarios is 17,000 euros. That’s why this document so often becomes relevant when it’s already too late to purchase it.
That’s why this document often becomes relevant only when it’s already too late to purchase it.
How to Choose the Right Policy
Not all civil liability insurance policies are the same. When choosing one, you should pay attention to a few things.
Insurance coverage limit. This is the maximum amount the insurer will pay out during the policy period. It must correspond to the scale of the properties you manage. When managing large or special structures, a small coverage amount may simply not be enough.
Deductible. Your share of the cost for each insured event. A lower deductible means a higher premium, and vice versa. You need to find a balance here.
Scope of coverage. Check whether the policy covers damage that occurs after the property is handed over, and what exclusions are in place. Some policies do not cover intentional acts or errors committed by individuals lacking the necessary qualifications.
Term of coverage. Since defects may become apparent later, find out whether the coverage includes claims filed after the work has been completed.
| Criteria | Minimum Policy | Broader Coverage |
|---|
| Insurance Amount | Lower, suitable for small properties | Higher, suitable for special structures |
| Deductible | Higher | Lower or more flexible |
| Damage after delivery | Often limited | More commonly included |
| Annual premium | Lower | Higher |
The easiest way to avoid confusion is to compare offers from several insurers in one place. On platforms like Draudykle.lt, you can compare prices and coverage terms, and an insurance consultant will explain in simple terms what a specific exclusion or deductible amount means. This makes it easier to see where the differences lie.
Common Mistakes
A few mistakes come up especially often.
First—the assumption that “if nothing has happened so far, nothing will happen in the future.” Liability can arise unexpectedly, and claims can come even years later.
Second—purchasing a policy merely as a formality, without reading the exclusions. The person has the document, but when a loss occurs, it turns out that this specific case is not covered.
Third—the coverage amount is too low. You save on the premium, but when liability actually arises, the amount isn’t enough, and you end up having to cover the difference yourself.
Tip: Before signing a new maintenance contract, check three things: whether the policy is valid, whether the coverage amount matches the scale of the property, and whether the specific risks that are most relevant to you have been excluded.
Fourth—procrastination. People try to purchase a policy only after a claim has already been filed. That’s not how it works. Insurance covers only those events that occur while the policy is in effect.
FAQ
Is insurance for a construction technical supervisor truly mandatory, or is it merely recommended? Civil liability insurance for technical supervision is established in the Construction Law as a mandatory requirement for carrying out the relevant activities. This is not a voluntary choice but a legal obligation, compliance with which may be required by both the client and the authorities.
How much does this insurance cost? The exact price depends on the coverage amount, the deductible, the scope of operations, and the type of properties being maintained. Prices vary by insurer, so it’s best to compare several quotes rather than rely on a single figure. The premium itself is usually modest compared to the potential damage.
Does the policy cover damage that occurs after the property has been handed over? It depends on the specific terms and conditions. Some policies cover claims filed after the work is completed, while others do not or have limitations. That is why it is important to read the sections on the coverage period and exclusions before purchasing a policy.
What should I do if I’m operating as a business rather than as an individual? This obligation also applies to legal entities that provide maintenance services. A company insures its civil liability, and the coverage amount is typically tailored to the scale of the projects being carried out.
What happens if a claim exceeds the coverage limit? The insurer compensates for reasonable damages up to the policy’s coverage limit. Any amount exceeding this limit would have to be covered by you. Therefore, the coverage amount must correspond to the actual risk of the sites under supervision—an amount that is too low leaves a gap.
In short
Civil liability insurance for a construction technical supervisor is not a bureaucratic formality, but a legal obligation and a real financial safeguard. Without it, a single serious claim could cost tens of thousands of euros out of your own pocket.
The bottom line is simple: You must have a valid policy in place before starting a project, rather than trying to find one after a claim for damages has already been filed.
If you’re not sure whether your coverage is sufficient, review the terms and compare offers from several insurers—this will clearly show you the differences in coverage amounts, deductibles, and scope of coverage.
Compare insurance prices in just a few minutes
Draudykle.lt will help you compare offers from the most popular Lithuanian insurers and purchase insurance online.
Compare prices →