Travel Insurance: When the European Health Insurance Card Isn't Enough
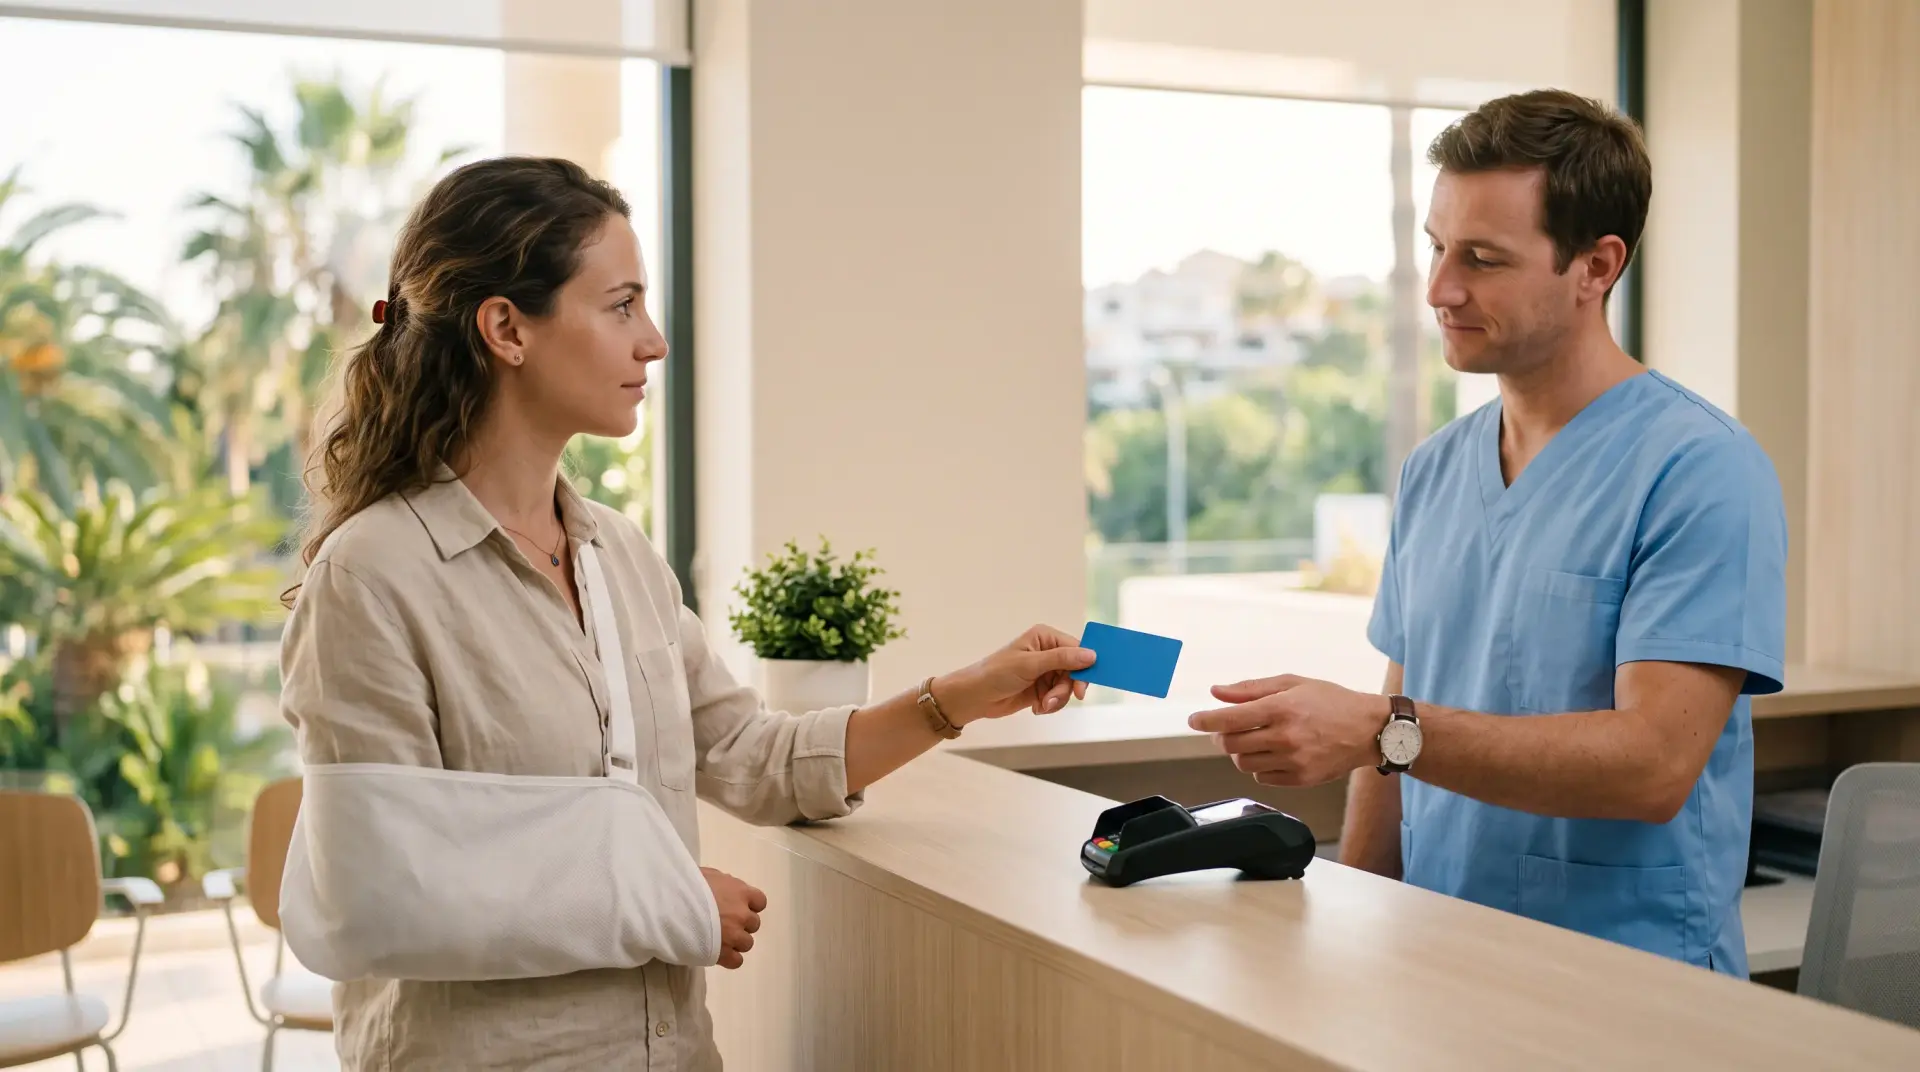
Imagine this: you’re on vacation on the Spanish coast, decide to try a jet ski, and unfortunately take a fall. A broken collarbone, an ambulance, a private clinic, several tests, and a day of observation. You present your European Health Insurance Card at the front desk—and find out that it isn’t valid here. The clinic is private. The bill comes to several thousand euros.
Many Lithuanians travel throughout the EU with only their EHIC and believe that’s enough. In part, this logic is correct—the card is indeed useful, and it’s free. But it covers a fairly narrow range of services, and the highest costs usually arise precisely where the card is no longer valid.
This article compares what the EHIC specifically covers versus what travel insurance covers, when you actually need both, and how much a mistake could cost.
In shortThe EHIC covers only public healthcare services in the EU under the same conditions as for local residents—it does not cover private clinics, medical repatriation to Lithuania (which can cost 10,000–70,000 EUR), lost luggage, trip cancellation, or sports injuries. When traveling within the EU, you need both: the EHIC plus travel insurance. Outside the EU, the EHIC is not valid at all.
What the EHIC Actually Covers—and What It Doesn’t
The European Health Insurance Card entitles you to receive public healthcare services in another EU or EEA country, or in Switzerland, under the same conditions as residents of that country. The whole point lies in those few words—“under the same conditions.”
Because if local residents pay a copayment for a doctor’s visit, you’ll have to pay one too. In some countries, the patient covers part of the treatment costs themselves, and the EHIC does not reimburse those costs. In France, for example, patients often pay out of pocket, and the government later reimburses a portion of the cost. For tourists, this reimbursement process can take weeks.
The card is not valid at private clinics. And in many resort areas, the ambulance takes you to the nearest private facility, not a public hospital.
And one more thing—perhaps the most important. The EHIC does not cover medical repatriation to Lithuania. If, after a serious injury, you need to be flown on a special flight accompanied by a doctor, that is entirely your responsibility.
Where does travel insurance coverage begin?
Travel insurance takes effect where the EHIC ends. A good policy typically covers:
- treatment at private clinics and public hospitals without copayments;
- medical evacuation to Lithuania (repatriation);
- lost, damaged, or delayed luggage;
- trip cancellation or interruption due to illness, the death of a close relative, or other specified reasons;
- civil liability if you cause harm to third parties;
- emergency dental care (usually with a coverage limit).
The coverage limit for medical expenses usually ranges from 30,000 to 100,000 EUR or more. For trips to the U.S. or Canada, it’s worth choosing a higher limit—medical treatment is particularly expensive there.
The deductible (or excess) is the amount you pay out of pocket when an insured event occurs. It can range from 0 to 50 EUR or more, depending on the policy.
ESDK and travel insurance are not alternatives—they cover different risks and work best together.
A Direct Comparison: What’s Covered and When
Many articles describe either ESDK or travel insurance separately. In reality, it’s more helpful to compare them side by side.
| Situation | ESDK | Travel insurance |
|---|
| Public hospital in the EU | Yes, under local conditions | Yes |
| Private clinic | No | Yes |
| Co-payments for treatment | Not covered | Most often covered |
| Medical repatriation to Lithuania | No | Yes |
| Lost luggage | No | Yes |
| Trip cancellation | No | Yes (subject to conditions) |
| Valid outside the EU/EEA | No | Yes |
| Sports Injuries | Limited / subject to local conditions | Yes, if included |
| Price | Free | Starting at a few EUR per day |
To be clear—they complement each other, not replace one another.
A concrete calculation: how much does a mistake cost?
Abstract warnings are rarely convincing. So here’s a concrete example.
Let’s say you’re traveling in Greece and suffer a serious injury. You need surgery, several days of treatment, and repatriation to Lithuania on a stretcher with a medical escort.
Example scenario in Greece (without travel insurance):

Treatment at a private clinic, surgery,
tests, medications (several days) ~ several thousand EUR
Medical repatriation to Lithuania
  (special flight with an escort) ~ 10,000–30,000 EUR
-----------------------------------------------------
Total without insurance ~ tens of thousands of EUR

With travel insurance:
Your out-of-pocket expenses (deductible) ~  0–50 EUR
The figures are approximate and depend on the country, distance, and your condition, but the scale is realistic. Medical repatriation from more distant countries can sometimes cost up to 70,000 EUR.
~10,000–30,000 EUR
Medical repatriation from the EU
up to 70,000 EUR
Repatriation from distant countries
from ~2–5 EUR per day
Cost of travel insurance
In other words, the cost of the policy is a tiny percentage of the potential risk.
Sports, skiing, and other hidden exclusions
Travel insurance for sports deserves special attention. A standard policy often DOES NOT COVER injuries sustained while engaging in active or risky activities.
Important: A classic travel insurance exclusion is alcohol. If an injury occurs while under the influence, most insurers will not pay out. The same applies to activities performed without protective gear or without an instructor when such equipment or supervision is required.
Common Mistakes to Avoid
Relying solely on the EHIC when traveling in the EU. The card is useful, but without coverage for repatriation and private clinics, the risk remains significant.
Not reading the exclusions. Many people are surprised to learn that chronic illnesses, pregnancy, or sports may not be covered without additional coverage.
“I thought the EHIC was enough. My son broke his leg in Croatia, and the ambulance took him to a private clinic. The card wasn’t valid, so I paid about 1,400 EUR. The following summer, we already had travel insurance—it cost less than 20 EUR,” says a traveler from Kaunas
Compare insurance prices in just a few minutes
Draudykle.lt will help you compare offers from the most popular Lithuanian insurers and purchase insurance online.
Compare prices →